
By Ben Eborn, Publisher, North American Potato Market News
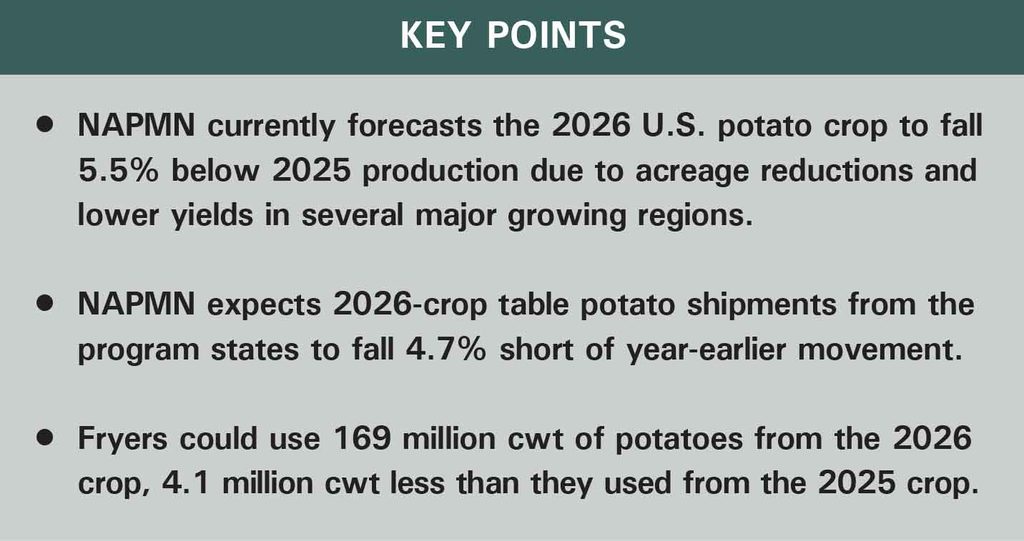
U.S. potato production in the reporting states is currently expected to fall 23 million cwt below production from the 2025 crop, according to North American Potato Market News’ estimate as of press time. Though overall production is projected to decline by 5.5%, we expect significant variation in production intended for each of the industry sectors.
Table 1 outlines our current usage projections for the 2026 crop, along with a three-year history of usage, as reported by USDA. Please note that relative demand between the industry sectors and market forces will alter the distribution of the 2026 potato crop relative to our current outlook. In the remainder of this article, we outline our projections for the various industry sectors in greater detail.
Fresh Potatoes
Program states shipped 87.8 million cwt of table potatoes from the 2025 crop. That is 3 million cwt, or 3.5%, more than they shipped a year earlier. We believe that supply conditions and market forces will encourage a reduction in 2026 crop-year shipments. NAPMN currently projects fresh potato sales from the 2026 crop to fall 4.7% short of 2025 movement. We expect most of the downturn in table potato sales to come from Idaho due to reduced yields and likely an increase in demand for open Russet Burbanks for the frozen processing sector. We also expect fresh sales to decline from several other shipping regions.
Early-season red potato shipments are down 14.9% from a year earlier. Red potato shipments will likely fall below the 2025-26 pace throughout the storage season. Early-season yellow potato shipments nearly match last year’s pace. Yellow potato shipments from the storage states could remain relatively flat this year.
The russet supply situation is complicated by its intersection with the processing industry. Early russet table potato shipments have been running 3.3% ahead of the 2025 pace. Slower early-season russet movement from Idaho has been offset by increased shipments from the San Luis Valley, northeast Colorado, Wisconsin, the Columbia Basin and Michigan. Russet table potato prices have improved significantly relative to year-earlier levels. Fresh Weighted Average (FWA) shipping point prices (as of press time) are up in each of the major shipping regions including Idaho (+81.1%), the San Luis Valley (+44.9%), the Columbia Basin (+55.4%) and Wisconsin (+29.6%). The Idaho Grower Returns Index (GRI) was unchanged during the week of Sept. 30, at $9.85 per cwt compared to only $3.10 per cwt a year earlier. Rising fuel costs have given packers closer to the eastern markets a substantial freight advantage during the past several months. Idaho marketers are struggling to compete with other major russet shipping regions. We expect reduced russet table potato movement and stronger prices throughout the 2026-27 marketing year.
Frozen Processing
Processors in the eight reporting states used 173.1 million cwt of potatoes from the 2025 crop for frozen processing. That is 9.8 million cwt more than year-earlier usage, a 6% increase.NAPMN expects fryers to use 169 million cwt of potatoes from the 2026 crop. That is 4.1 million cwt less than last year’s reported usage, a 2.4% reduction. We expect a downturn in frozen processing due to a limited supply of raw product from the 2026 crop. The planted area for frozen processing potatoes is down in several states. In addition, we currently project that yields will be down from last year in most of the processing states including Idaho, Washington, Oregon, Minnesota and North Dakota. We also believe the expected reduction will partially be caused by uncertain domestic and export demand for French fries and other frozen potato products. North American fryers shipped 7% less frozen potato products to offshore markets during the year ending June 30 than they did a year earlier.
Though 2026 potato production is currently estimated to be down close to 25% in the European Union, North American fryers will continue to face strong competition from China, India, Argentina and other exporters during the 2026-27 processing season. Local supplies could be tight for processors in the Pacific Northwest. Fryers may pull some Russet Burbank potatoes from Idaho’s flex pile. Challenging harvest conditions and expanded processing capacity in Alberta, along with rising transportation costs, will likely prevent a substantial volume of Canadian raw product from flowing south.
Dehydration
Dehydrators in the reporting states used 42.1 million cwt of potatoes from the 2025 crop. That is 1% less than the year-earlier volume, according to USDA reports. We expect dehydrators in the eight reporting states to use 36 million cwt of potatoes from the 2026 crop. That is 6.1 million cwt less than they used from the 2025 crop, a 14.6% reduction. It falls 17.9% below the three-year average pace.
Though we do not have reliable data for domestic dehydrated product sales, offshore sales remain sluggish. Reported U.S. potato flake exports during the year ending July 31 fell 10.2% short of the previous year’s sales volume. That was the smallest U.S. potato flake export volume for the period since 2009-10. Growers in Idaho and across the country indicate that demand for off-grade potatoes has been extremely soft. Dehydrators also made significant contract reductions for both field-delivery and storage potatoes from the 2026 crop. Dehy processing use could fall below our estimate if finished-product demand does not pick up.
Other Eight States Processing Use
This is the difference between total processing use reported for the eight states and usage reported for dehydration and frozen products. It may include usage at chip plants in the reporting states, as well as other miscellaneous uses. At 12 million cwt, usage in this category would fall 13.9%.
Other Processing Use
This is the difference between total processing use reported for the program states and usage reported for the eight processing states. This is where most of the program states’ chip potato usage would show up. At 34 million cwt, we are projecting a 3.9 million cwt reduction in 2026-crop processing use outside of the eight reporting states. Despite the relatively large 10.3% decline, the projected usage downturn in this category is less than last year’s reduction, which was 20.6%. Chip potato usage could vary from our projection depending on finished product demand shifts.
Seed Potatoes
Reported seed potato shipments from the 2025 crop totaled 18.7 million cwt, down 8% from the previous year. Rapidly rising production costs and thin profit margins will likely encourage acreage reductions in 2027. At 18 million cwt, NAPMN expects 2026 seed movement from the program states to decline by 3.5% relative to the 2025 crop.